
Giving money to your children or grandchildren can seem like one of the simplest ways to reduce the value of your estate.
But how much can you actually give away without creating an inheritance tax problem?
The answer is more complicated than simply staying below one annual limit.
UK inheritance tax rules contain several gifting exemptions, and understanding how they work can help you distinguish between gifts that are immediately outside your estate and gifts that may remain relevant for inheritance tax purposes for several years.
The £3,000 Annual Gift Exemption
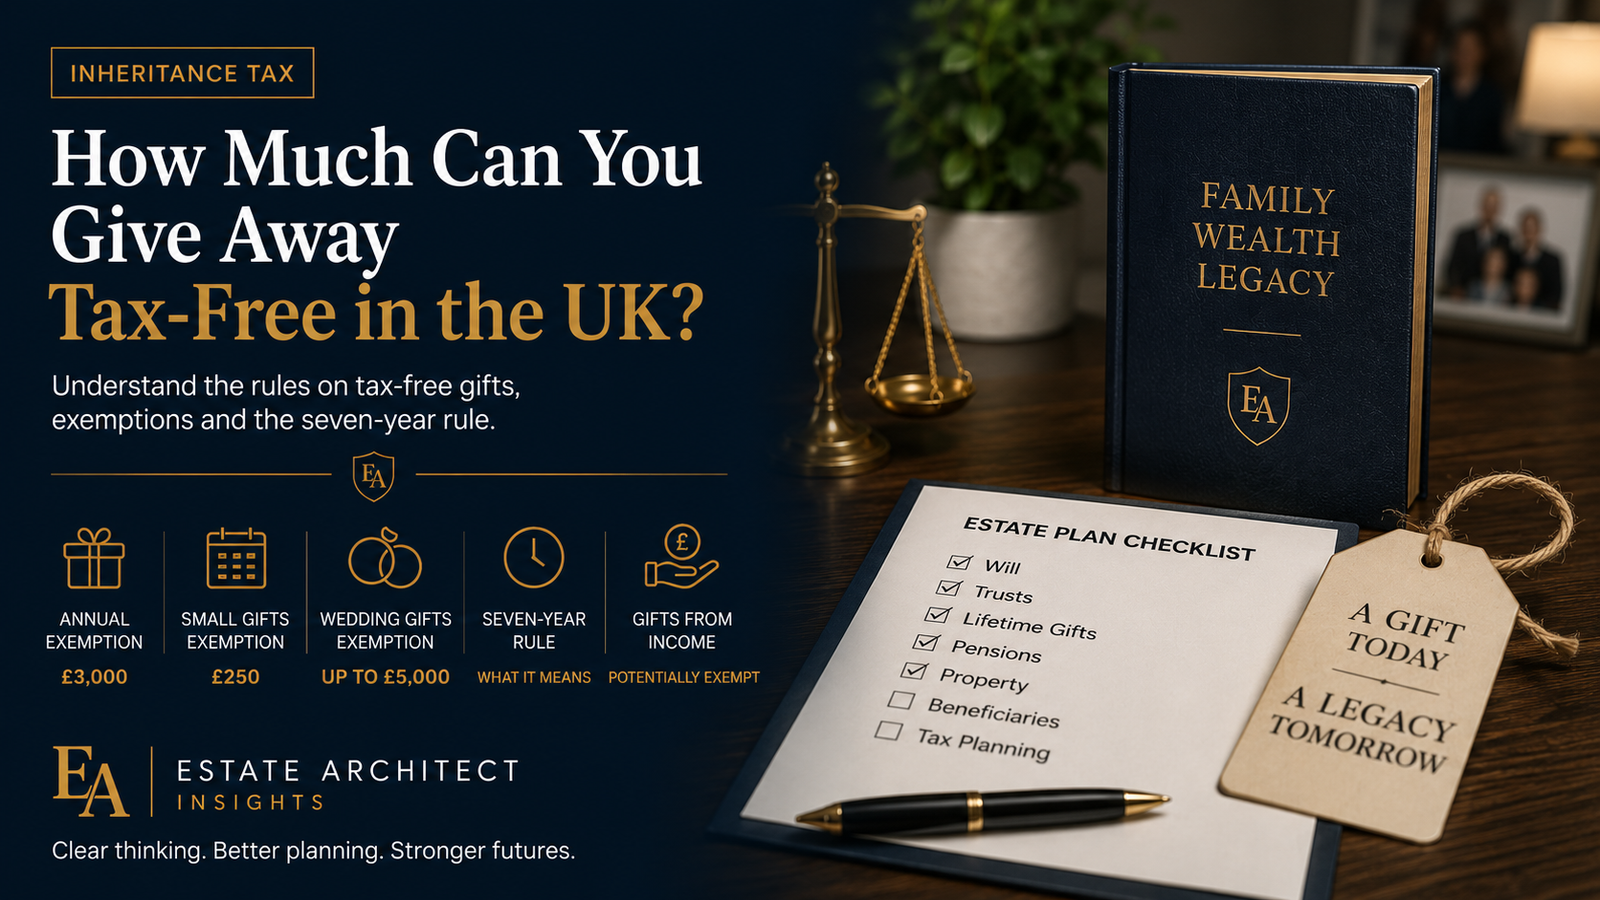
You can normally give away up to £3,000 each tax year using your annual inheritance tax exemption.
These gifts are immediately exempt from inheritance tax.
If you did not use your £3,000 exemption in the previous tax year, you can normally carry it forward for one tax year only.
That means you could potentially give away £6,000 using the current year’s exemption together with an unused exemption carried forward from the previous year.
For a married couple or civil partners, each person has their own exemption.
Can You Give More Than £3,000?
Yes.
The £3,000 allowance does not mean that you are prohibited from giving away more than £3,000.
You can potentially give away much larger amounts.
However, gifts that do not fall within an exemption will commonly be treated as Potentially Exempt Transfers (PETs) when made directly to another individual.
This is where the seven-year rule becomes important.
The Seven-Year Rule
If you make a gift to an individual and survive for seven years after making it, the gift will generally fall outside your estate for inheritance tax purposes.
If you die within seven years, the gift may need to be considered when calculating the inheritance tax position of your estate.
This is why keeping accurate records of significant lifetime gifts is important.
It is also worth remembering that taper relief does not simply reduce the value of the gift after three years. Where applicable, it reduces tax payable on certain gifts, and its effect depends on the circumstances.
Small Gifts
There is also a small gift exemption.
You can give up to £250 per person per tax year to as many people as you wish, provided you have not used another allowance on the same person.
For families with several children or grandchildren, this can provide another straightforward way of making smaller gifts.
Wedding and Civil Partnership Gifts
Certain gifts made for a wedding or civil partnership can also qualify for an exemption.
The limits depend on your relationship to the recipient:
- £5,000 to a child
- £2,500 to a grandchild or great-grandchild
- £1,000 to anyone else
These exemptions can potentially be used alongside other available exemptions where the relevant conditions are satisfied.
Regular Gifts From Income
One of the most useful — and sometimes overlooked — inheritance tax exemptions relates to normal expenditure out of income.
Regular gifts may potentially be exempt immediately if, broadly, they:
- form part of your normal expenditure,
- are made from your income, and
- leave you with sufficient income to maintain your normal standard of living.
Unlike the seven-year rule, qualifying gifts under this exemption can potentially fall outside the estate immediately.
This can make the exemption particularly relevant to people whose income consistently exceeds what they need to fund their lifestyle.
Good record-keeping is important because your executors may ultimately need to demonstrate that the conditions were satisfied.
What If You Give Away Your House?
Property requires particular care.
Simply transferring your home to your children does not necessarily remove it from your estate.
If you give away your house but continue living there without paying an appropriate market rent, the gift with reservation of benefit rules may mean that the property remains within your estate for inheritance tax purposes.
So giving an asset away legally and removing it from your estate for inheritance tax purposes are not necessarily the same thing.
Should You Give Assets Away Just to Reduce Inheritance Tax?
Tax should not be the only consideration.
Once an asset has genuinely been given away, you may lose control over it.
The recipient’s circumstances can also change through divorce, bankruptcy, financial difficulties or death.
And you still need enough assets and income to support your own lifestyle throughout retirement.
The objective should therefore not simply be to give away as much as possible.
It is to understand how gifting fits within your wider estate and financial position.
Keep Records of Your Gifts
If you make significant gifts, maintain a clear record showing:
what you gave, who received it, the value, the date and which exemption you believe applies.
Years later, your executors may need this information when dealing with your estate.
Good estate planning is not only about making the right decisions. It is also about leaving enough evidence for those decisions to be understood after your death.
How Much Could You Give Away?
Lifetime gifting can be a useful part of inheritance tax planning, but the amount you can afford to give away may be very different from the amount the tax rules allow you to give.
Estate Architect can help you understand your potential inheritance tax exposure and how gifting fits alongside your property, pensions, investments and wider estate.