
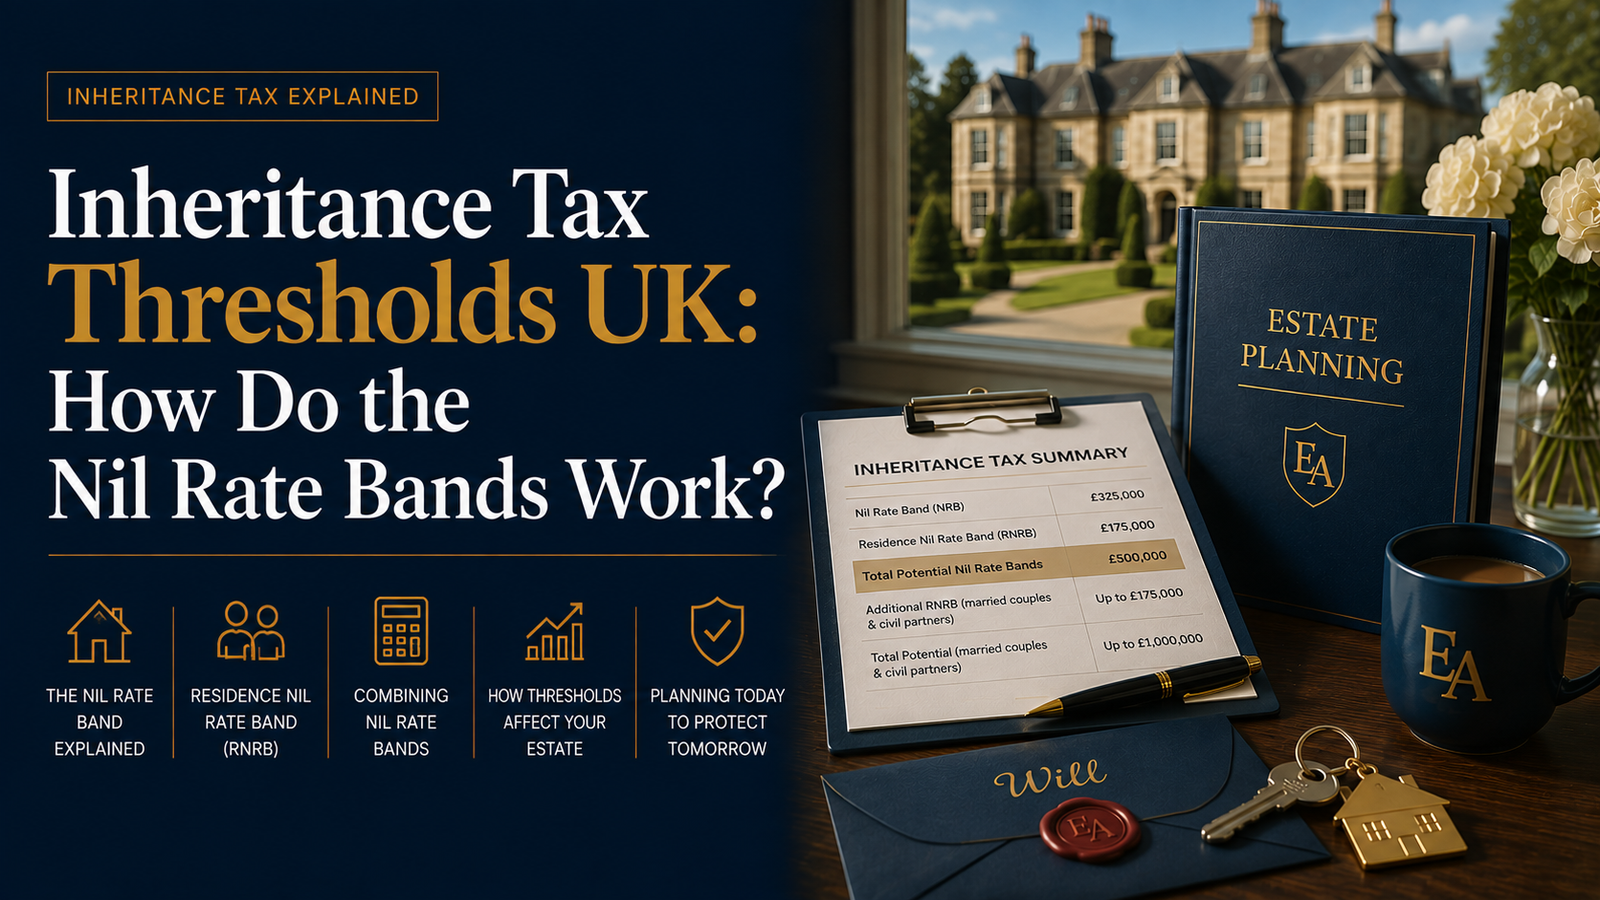
Inheritance tax is often described as a 40% tax on estates above £325,000.
But that description is incomplete.
Depending on your circumstances, your estate may potentially benefit from more than one inheritance tax allowance. Married couples and civil partners may also be able to transfer unused allowances between them.
At the same time, some estates can lose part or all of an important allowance as their value increases.
So before asking “How much inheritance tax will I pay?”, it is useful to understand how the main inheritance tax thresholds actually work.
What Is the Inheritance Tax Nil-Rate Band?
The nil-rate band is the basic inheritance tax threshold.
For the 2025/26 tax year, it is £325,000.
Broadly, this means that the first £325,000 of a person’s taxable estate can potentially fall within the nil-rate band and be taxed at 0%.
Inheritance tax is normally charged at 40% on the taxable value above the available threshold, although exemptions and reliefs can alter the calculation.
A very simple example:
Estate value: £800,000
Nil-rate band: £325,000
Remaining amount: £475,000
Ignoring every other allowance, exemption, relief and deduction, 40% of £475,000 would be £190,000.
But for many families, that is not the complete calculation.
What Is the Residence Nil-Rate Band?
There is potentially an additional allowance known as the residence nil-rate band, or RNRB.
For the 2025/26 tax year, the maximum RNRB is £175,000 per person.
Broadly, it may be available where a qualifying residence is passed to qualifying direct descendants, subject to the relevant conditions.
That can potentially increase an individual’s combined allowances from:
£325,000 → £500,000
But the additional £175,000 should not simply be assumed to apply to every estate.
The circumstances need to qualify.
Could a Married Couple Have £1 Million of Allowances?
Potentially, yes.
Unused nil-rate band can generally be transferred between spouses or civil partners when the second person dies.
The same principle can potentially apply to unused residence nil-rate band.
This creates the often-quoted potential £1 million inheritance tax threshold for a qualifying married couple or civil partnership:
| Allowance | Potential amount |
|---|---|
| Nil-rate band — first spouse | £325,000 |
| Nil-rate band — second spouse | £325,000 |
| Residence nil-rate band — first spouse | £175,000 |
| Residence nil-rate band — second spouse | £175,000 |
| Potential total | £1,000,000 |
But there is an important word here:
Potential.
Not every couple will qualify for the full £1 million.
Why £1 Million Is Not an Automatic IHT Allowance
The £1 million figure can create a false sense of security.
The residence nil-rate band has conditions attached to it.
For example, the estate generally needs to include a qualifying residence and the property needs to pass in a qualifying way to direct descendants.
Family circumstances and previous use of allowances can also affect the position.
And there is another major issue:
the size of the estate itself.
What Happens When an Estate Exceeds £2 Million?
The residence nil-rate band can begin to reduce where the estate exceeds £2 million.
This is known as the RNRB taper.
Broadly, the residence nil-rate band is reduced by £1 for every £2 by which the estate exceeds the £2 million threshold.
This can produce a surprising result.
As an estate becomes wealthier, it can potentially lose an allowance that the family expected to receive.
For someone potentially entitled to a £175,000 RNRB, the allowance could eventually disappear entirely once the relevant estate value reaches a sufficiently high level.
For a qualifying couple with transferred RNRB, the figures can be even more significant.
Why Estate Growth Matters
Inheritance tax planning should not look only at what an estate is worth today.
Suppose an estate is currently worth £1.8 million.
It may currently sit below the £2 million RNRB taper threshold.
But if property and investments continue to appreciate, the estate could move above £2 million later.
That could potentially create two effects at the same time:
1. The taxable estate becomes larger.
2. The available residence nil-rate band may begin to reduce.
This is why future estate growth can matter almost as much as today’s valuation.
Do Gifts Affect the Nil-Rate Band?
Lifetime gifts can also interact with inheritance tax calculations.
Some gifts may be immediately exempt, while others can remain relevant for inheritance tax purposes for a period after they are made.
The timing, nature and circumstances of a gift can therefore matter.
This is also why maintaining proper records of significant lifetime gifts is useful.
Executors may need those records many years later.
What About Property Ownership?
Property is particularly relevant because it can affect both:
- the overall value of the estate; and
- potential eligibility for the residence nil-rate band.
A valuable home can therefore increase an estate’s inheritance tax exposure while potentially also providing access to an additional allowance where the relevant conditions are satisfied.
The important point is that property value alone does not tell you your inheritance tax position.
Ownership, beneficiaries and the wider estate all need to be considered.
Why Two £1.5 Million Estates Could Pay Different Amounts
Imagine two families with estates worth exactly the same amount.
Both are worth £1.5 million.
That does not necessarily mean their inheritance tax liability will be identical.
One might have:
- transferable allowances from a deceased spouse;
- a qualifying residence passing to children;
- relevant exemptions or reliefs.
The other might not.
Inheritance tax therefore depends on considerably more than the headline estate value.
The Four Numbers Worth Knowing
For a basic understanding of the UK inheritance tax thresholds, these are four important figures:
£325,000 — standard nil-rate band per individual.
£175,000 — maximum residence nil-rate band per individual where qualifying conditions are met.
£500,000 — potential combined individual threshold where the full RNRB is available.
£2 million — the point at which the residence nil-rate band can begin to taper.
These figures provide a starting point.
They are not a substitute for calculating the position of an individual estate.
Don’t Just Ask Whether Your Estate Is Above the Threshold
A better set of questions is:
What is my estate actually worth?
Which allowances could potentially apply?
Would my estate qualify for the residence nil-rate band?
Could estate growth eventually push me into the £2 million taper?
Have previous gifts affected the calculation?
Are transferable allowances potentially available?
These questions provide a much clearer picture than simply comparing your house value with £325,000.
Understand Your Potential Inheritance Tax Exposure
Inheritance tax thresholds can look simple until property, spouses, beneficiaries, gifts and estate growth are added to the calculation.
Estate Architect looks at how these different elements fit together and helps identify potential weaknesses or areas requiring further investigation.
Book a Consultation with Ranjeet →
Estate Architect provides educational research and analysis relating to inheritance tax and estate planning concepts for UK residents. We do not provide regulated investment, tax or legal advice and are not authorised or regulated by the Financial Conduct Authority (FCA). Where regulated advice is required, introductions may be made to authorised professionals.